
Author: 0xFacai, Blockbeats
We have previously mentioned that in September, on-chain options notional volume reached 4.829 billion USD, a month-over-month increase of 121.7%; monthly premium volume also grew from over twenty million USD at the beginning of the year to over eighty million USD. Hyperliquid founder Jeff publicly discussed the development opportunities for options.
However, many crypto-native traders have long been accustomed to the way perpetual contracts work. If bullish, open a long; if bearish, open a short; deposit margin, and open and close positions at any time. Switching to the options interface, facing rows of strike prices, expiration dates, and Greek letters, the urge to trade is half consumed by the complex operations before it even begins.
The newly announced Power Perps from HIP-3 trading platform Paragon offers another entry point. Starting with HYPE², it lets traders obtain option-style payoff curves by "opening contracts."
No strike price, no expiration date. You are still trading a perpetual contract, except that the price it tracks has become the square of HYPE.
Convexity
The payoff of an ordinary perpetual contract is a straight line. Holding a fixed number of long positions, for every 1 USD the underlying rises, the money earned is the same; for every 1 USD it falls, the money lost is also the same. Adding leverage makes this straight line steeper, but the shape remains unchanged.
"N-th power contracts" change this.
For ease of calculation, assume an asset is priced at 100 USD when listed, and the price of the squared contract also starts at 100.
The underlying rises to 110, the index reaches 121, an increase of 21%; the underlying falls to 90, the index falls to 81, a decrease of 19%. For the same 10% price change, longs earn a little more when it rises and lose a little less when it falls.
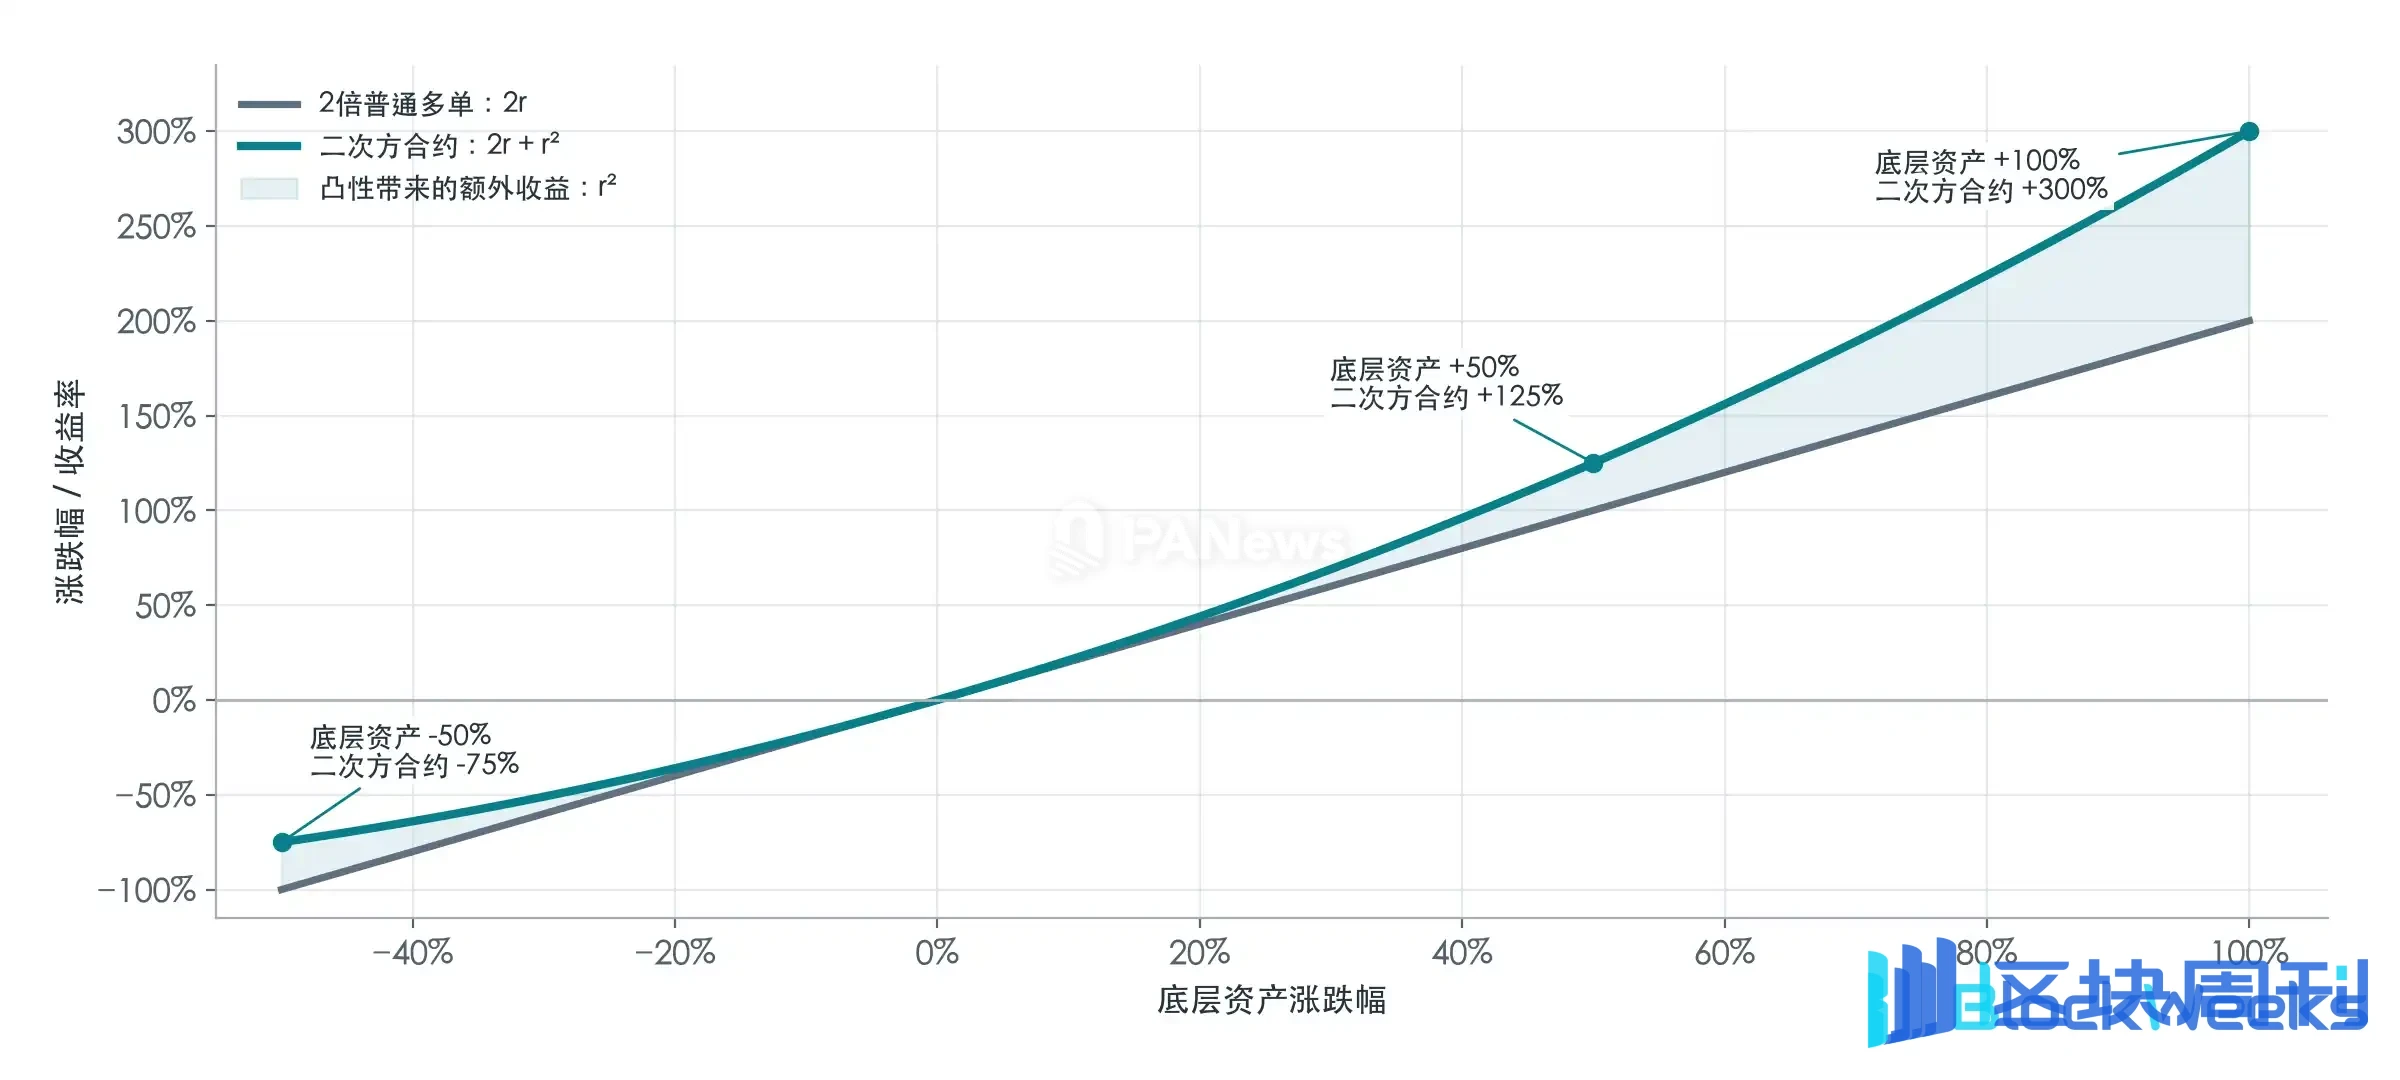
Widen the price move, and the difference becomes more obvious. The underlying rises 50%, the squared index rises 125%; the underlying falls 50%, the index falls 75%. If the underlying doubles, the index becomes four times the original. Cubic contracts go further: if the underlying doubles, the index becomes eight times the original.
Assume the underlying's percentage change is r:
Percentage change of the squared contract = 2r + r²
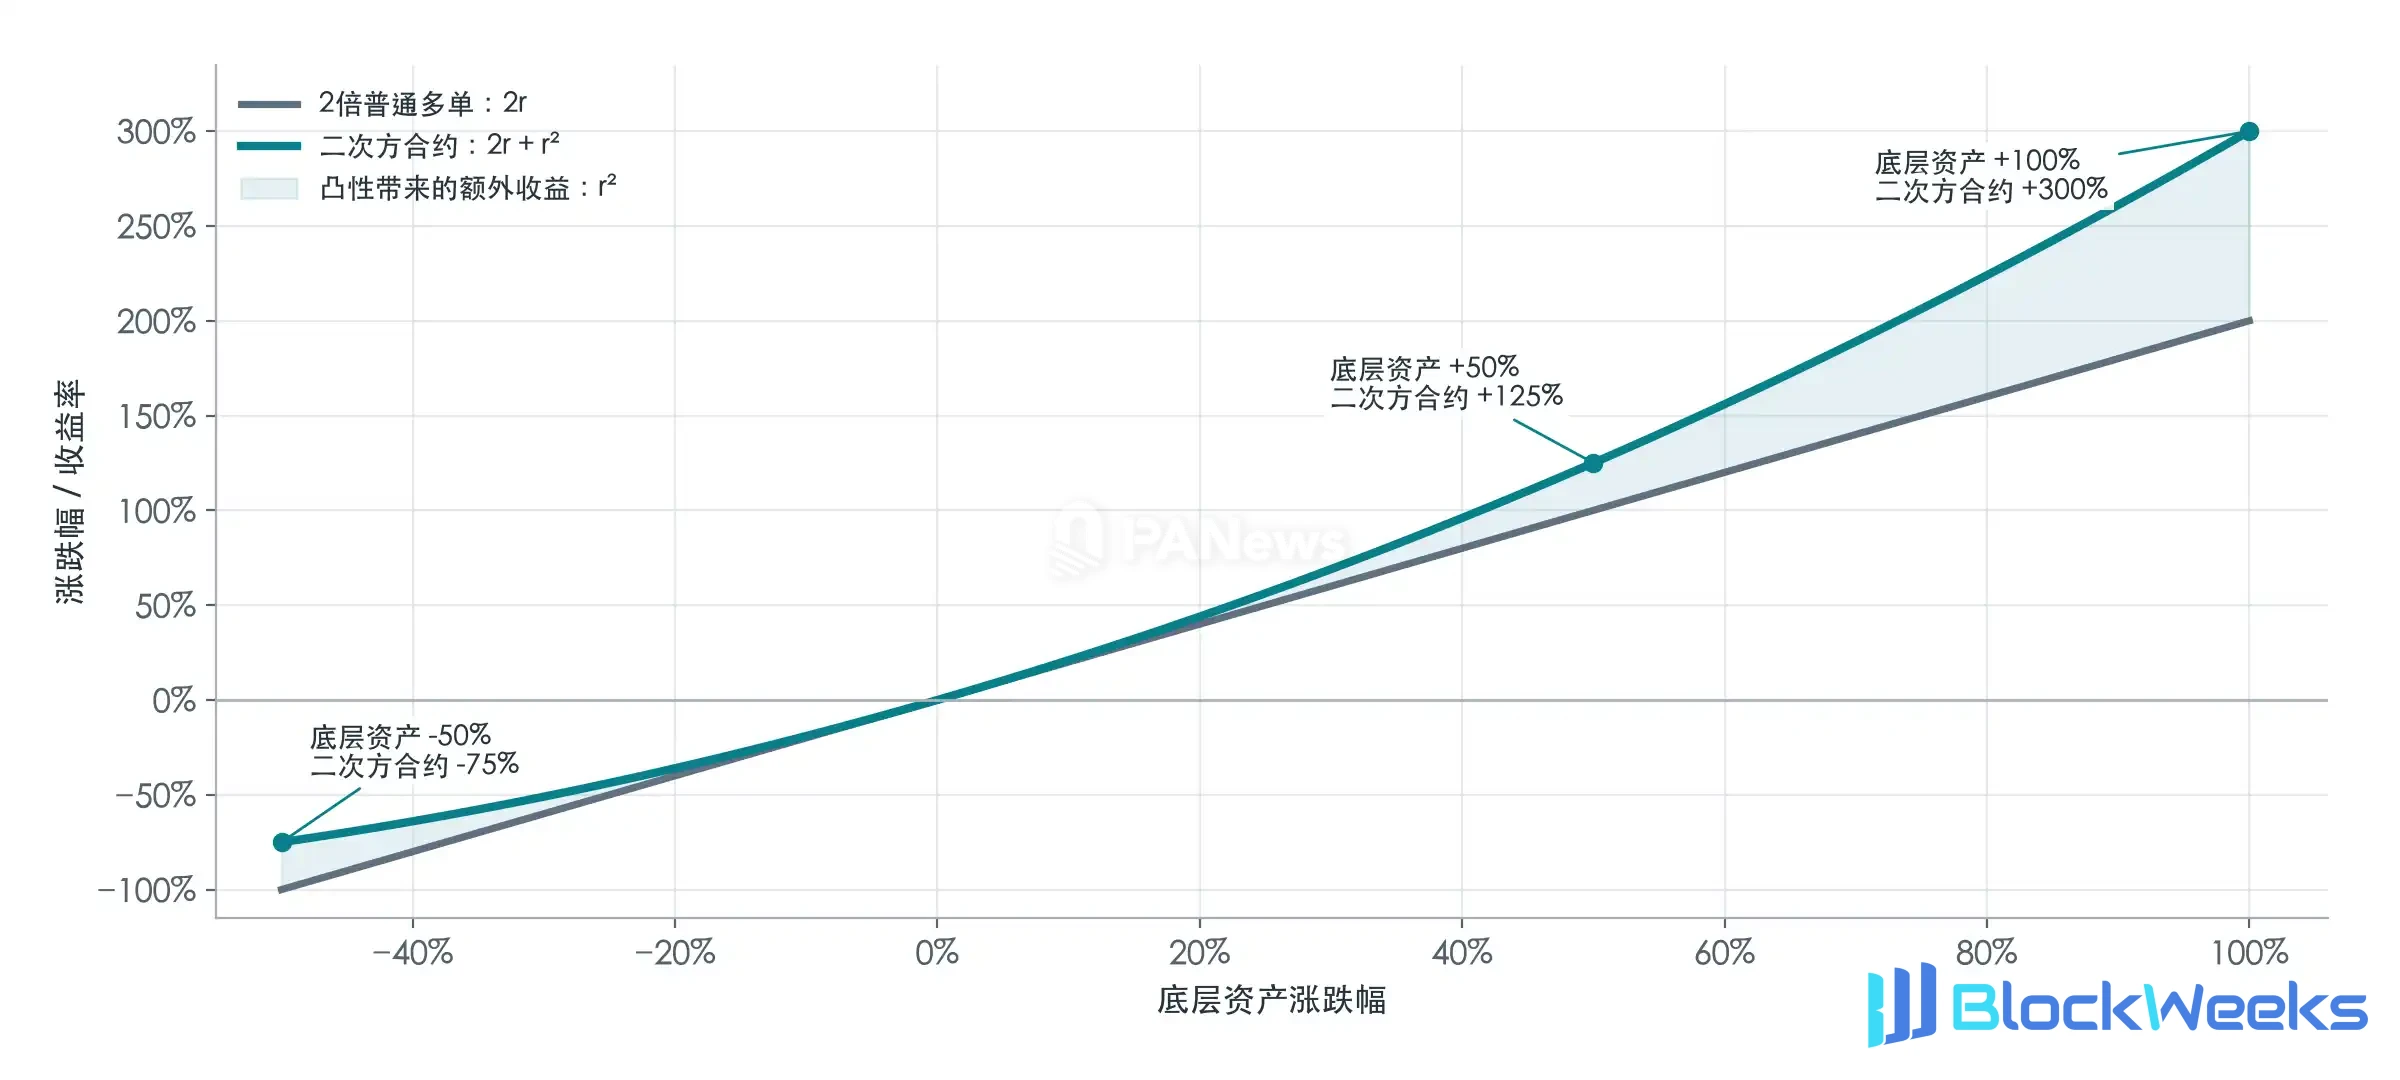
The leading 2r provides the return magnitude of a 2x leveraged long; the trailing r² is never less than zero regardless of rise or fall, so compared with 2x long, it can increase returns when rising and reduce losses when falling, and the larger the price move, the greater this difference.
This is "convexity." Moving upward along the squared curve, for every additional 1 USD rise, longs earn more than on the previous 1 USD; moving downward, for every additional 1 USD fall, the loss is less than on the previous 1 USD. The sensitivity of a squared contract changes automatically with price, which ordinary contracts cannot do.
What options traders are willing to buy includes precisely this "convexity."
This idea already had a theoretical foundation as early as 2021. Paradigm's Everlasting Options discussed how to use continuous funding fees to maintain "never-expiring" options exposure, and the subsequent Power Perpetuals article used powers of price as the tracking target. Opyn later practiced this with Squeeth tracking ETH², and Paragon wants to bring this type of product to Hyperliquid's order book.
In addition, the trading demand for traditional options is dispersed across many contracts with different strike prices and expiration dates, making liquidity highly fragmented. "N-th power contracts" allow traders of the same underlying and same power to share a single order book.
Funding Rate
At this point, it is easy to have a thought. Squared contracts rise faster and fall slower—what is the cost of this benefit?
Let us do an experiment with both long and short open. Suppose a trader, when the price is 100, simultaneously opens one squared long and hedges with two units of ordinary short contracts on the underlying asset. The underlying asset rises from 100 to 110, the squared long earns 21, the linear short loses 20, for a total gain of 1. The underlying asset falls from 100 to 90, the squared long loses 19, the linear short earns 20, for a total gain of 1 again. If it rises to 120 or falls to 80, both cases gain 4.
Written as a formula, the profit and loss of this long-short combination is:
Price P&L of the long-short combination = square of the difference between the underlying asset price and 100 ÷ 100

If there were no funding rate, traders could arbitrage for free in the above manner.
But the "no-arbitrage principle" requires that such a benefit must have a price, namely the funding rate.
It is easier to understand from the market maker's side. A market maker sells one squared contract and simultaneously buys two units of the underlying asset to hedge. The underlying rises 10 USD, the market maker's short loses 21, while the hedged spot only earns 20, for a net loss of 1; the underlying falls 10 USD, the short earns 19, while the hedged spot loses 20, also a net loss of 1. This is exactly the "arbitrage" profit on the other side.
The market maker also has to continue adjusting the hedge quantity as the price changes. After each adjustment, the next price move will again produce P&L related to the square of the percentage change. Accumulating these squares gives the "variance" here. The more violently the price moves back and forth, the higher the hedging cost the market maker bears for providing convexity.
Therefore, in addition to the holding cost of ordinary contracts, longs in N-th power contracts also need to continuously pay for convexity. This portion of the fee is related to variance (the square of volatility) and is usually paid by longs to shorts. The premium or discount in the order book will also affect the final funding rate.
Liquidation
Still starting from 100 USD, put up 100 USD of principal and compare a 2x long with a fully collateralized squared long worth 100 USD.
The underlying falls from 100 to 50, the loss on the 2x long is 100 USD, the principal is already wiped out, and actual liquidation would be triggered even earlier. Ignoring funding rates and losses from other cross-margin positions, the squared long at this point falls from 100 to 25 and still retains 25 USD of equity, and will not be liquidated merely because of a price decline.
A fully collateralized squared long gives traders about twice the initial price sensitivity while avoiding liquidation caused by a pure price decline.
But once leverage is added on top of a squared contract, liquidation approaches quickly. According to the example in Paragon's risk documentation, temporarily ignoring accumulated funding fees and other account assets, a 2x HYPE² long will be liquidated when HYPE falls by about 22.5%, and a 3x HYPE² long will be liquidated after a decline of only about 10.6%.

The short side needs to be even more careful. The more the price rises, the faster a quadratic short loses, and even a 1x quadratic short will be liquidated.
Volatility Trading
The combination of a quadratic long paired with a linear short described earlier can also be turned into a trading strategy. You don't need to judge whether the price will go up or down next; you only need to judge whether the price will move far enough away from its current position.
In traditional options, buying a call and a put with the same strike price and the same expiration date forms a "straddle." When there is a big rally, the call option makes money; when there is a big drop, the put option makes money—there are profit opportunities in both directions. Power Perps, using a quadratic long paired with a linear short, can also piece together a payoff curve that slopes upward on both sides.

This is an intuitive entry point for going long volatility. Both big rallies and big drops can bring opportunities, but the price needs enough volatility to offset the funding fee cost.
Conversely, by shorting quadratic contracts and then buying a corresponding amount of the underlying asset or linear longs to hedge, you can go short volatility. If the price stays near the opening position, the funding fees collected by the quadratic short contracts have a chance to become profit; once there is a big rally or a big drop, the loss after hedging will increase with the square of the magnitude of the move.
However, the "no expiration date" feature of quadratic contracts also means that the holding cost of funding fees can accumulate indefinitely.
Power Perps also cannot replicate all traditional options strategies exactly. A strangle combination requires two different strike prices, one above and one below; spread strategies can set a profit cap and a loss floor through different strike prices; covered calls and covered puts also require selling options at specified strike prices, giving up part of the profit potential in the corresponding direction in exchange for the premium.
These strategies all have payoff inflection points delineated by strike prices, and usually also specify an expiration time. Quadratic contracts paired with linear positions produce a smooth curve. By adjusting the position ratio, you can approximate some options strategies within a certain price range; but if you want to precisely specify "cap the payoff once it rises to a certain price" or "keep the payoff unchanged within a certain range," options are still indispensable.
The price of simplified operations and concentrated liquidity is the loss of some freely selectable payoff structures.
The Evolution of the "Listing" Strategy
Hyperliquid provides the order book, spot markets, and margin system, while Paragon designs new payoff curves on top of these foundations. Market makers can hedge more conveniently, and developers can continue to package combinations into strategies, reducing the operations of traders having to build and adjust positions themselves.
Traditional options have already proven that the market has long-term demand for different payoff structures. The value of Paragon's attempt this time lies in expressing part of that demand in a way familiar to crypto-native traders, and also allowing existing perpetual liquidity to provide hedging for new products.
The trend more worth watching is that the "listing" of HIP-3 exchanges has evolved from selecting traditional financial assets with hype to creating new forms of derivatives. I look forward to seeing more such new financial experiments on Hyperliquid.