Issue 23 closed on a disclosed buyer spending down a published balance and a long end that had moved on an empty calendar, and asked what the next filing would fund and whether the thirty-year would close above 5.50%. The filing went back to share sales, and the thirty-year was above the line at the close of the first session [1][2].
The single most useful fact in this issue is how the buyer paid. The filing that covers September 21 to 27 records $246.2m of net proceeds from common-stock sales under the at-the-market programme, after three filings without any, and states where they went: $142.7m to 1,665 bitcoin at an average of $85,681 including fees, and $103.5m to repurchases of the company's Stretch preferred, with a further $48.1m of USD Cash paid toward the same repurchases [1]. USD Cash ended the period at $1.00bn, the line Issue 23 drew. Issue 23 said one filing could restore the pattern of selling stock; the next one did, and 42.0% of what the stock raised went to buying back the company's own preferred.
The long end kept rising, and this time through a full calendar. The thirty-year closed every session above 5.50%, set a 2026 high of 5.64% on September 30 and ended the window 14 basis points higher; the two-year ended 2 higher [2]. The window carried JOLTS, the August PCE report with the third estimate of second-quarter GDP, and a September payroll gain of 29,000 with the two prior months revised down by 60,000 [8][9][10][11]. The 2s30s spread widened from 68 basis points to 80.
Bitcoin's five weekdays added 0.06%; its weekend added 2.37%. The window ended +2.43% at 86,482.80, its highest close, and the gain came on the two sessions with the least volume traded in the window [3]. Leverage split by venue: Binance open interest ended 3.61% higher and Bybit's 3.02% lower, and Bybit printed a negative daily funding total on Saturday, the first on either venue since September 5 [4][5][6][7].
Two more items complete the issue. Section 5 corrects three sentences in Issue 22, and section 6 sets out the dates the stablecoin law's rulebook now runs on, published in the Federal Register in this window [12][13][14].
Week of September 28 to October 4, 2026
Bitbase Research · October 5, 2026
The one chart that matters
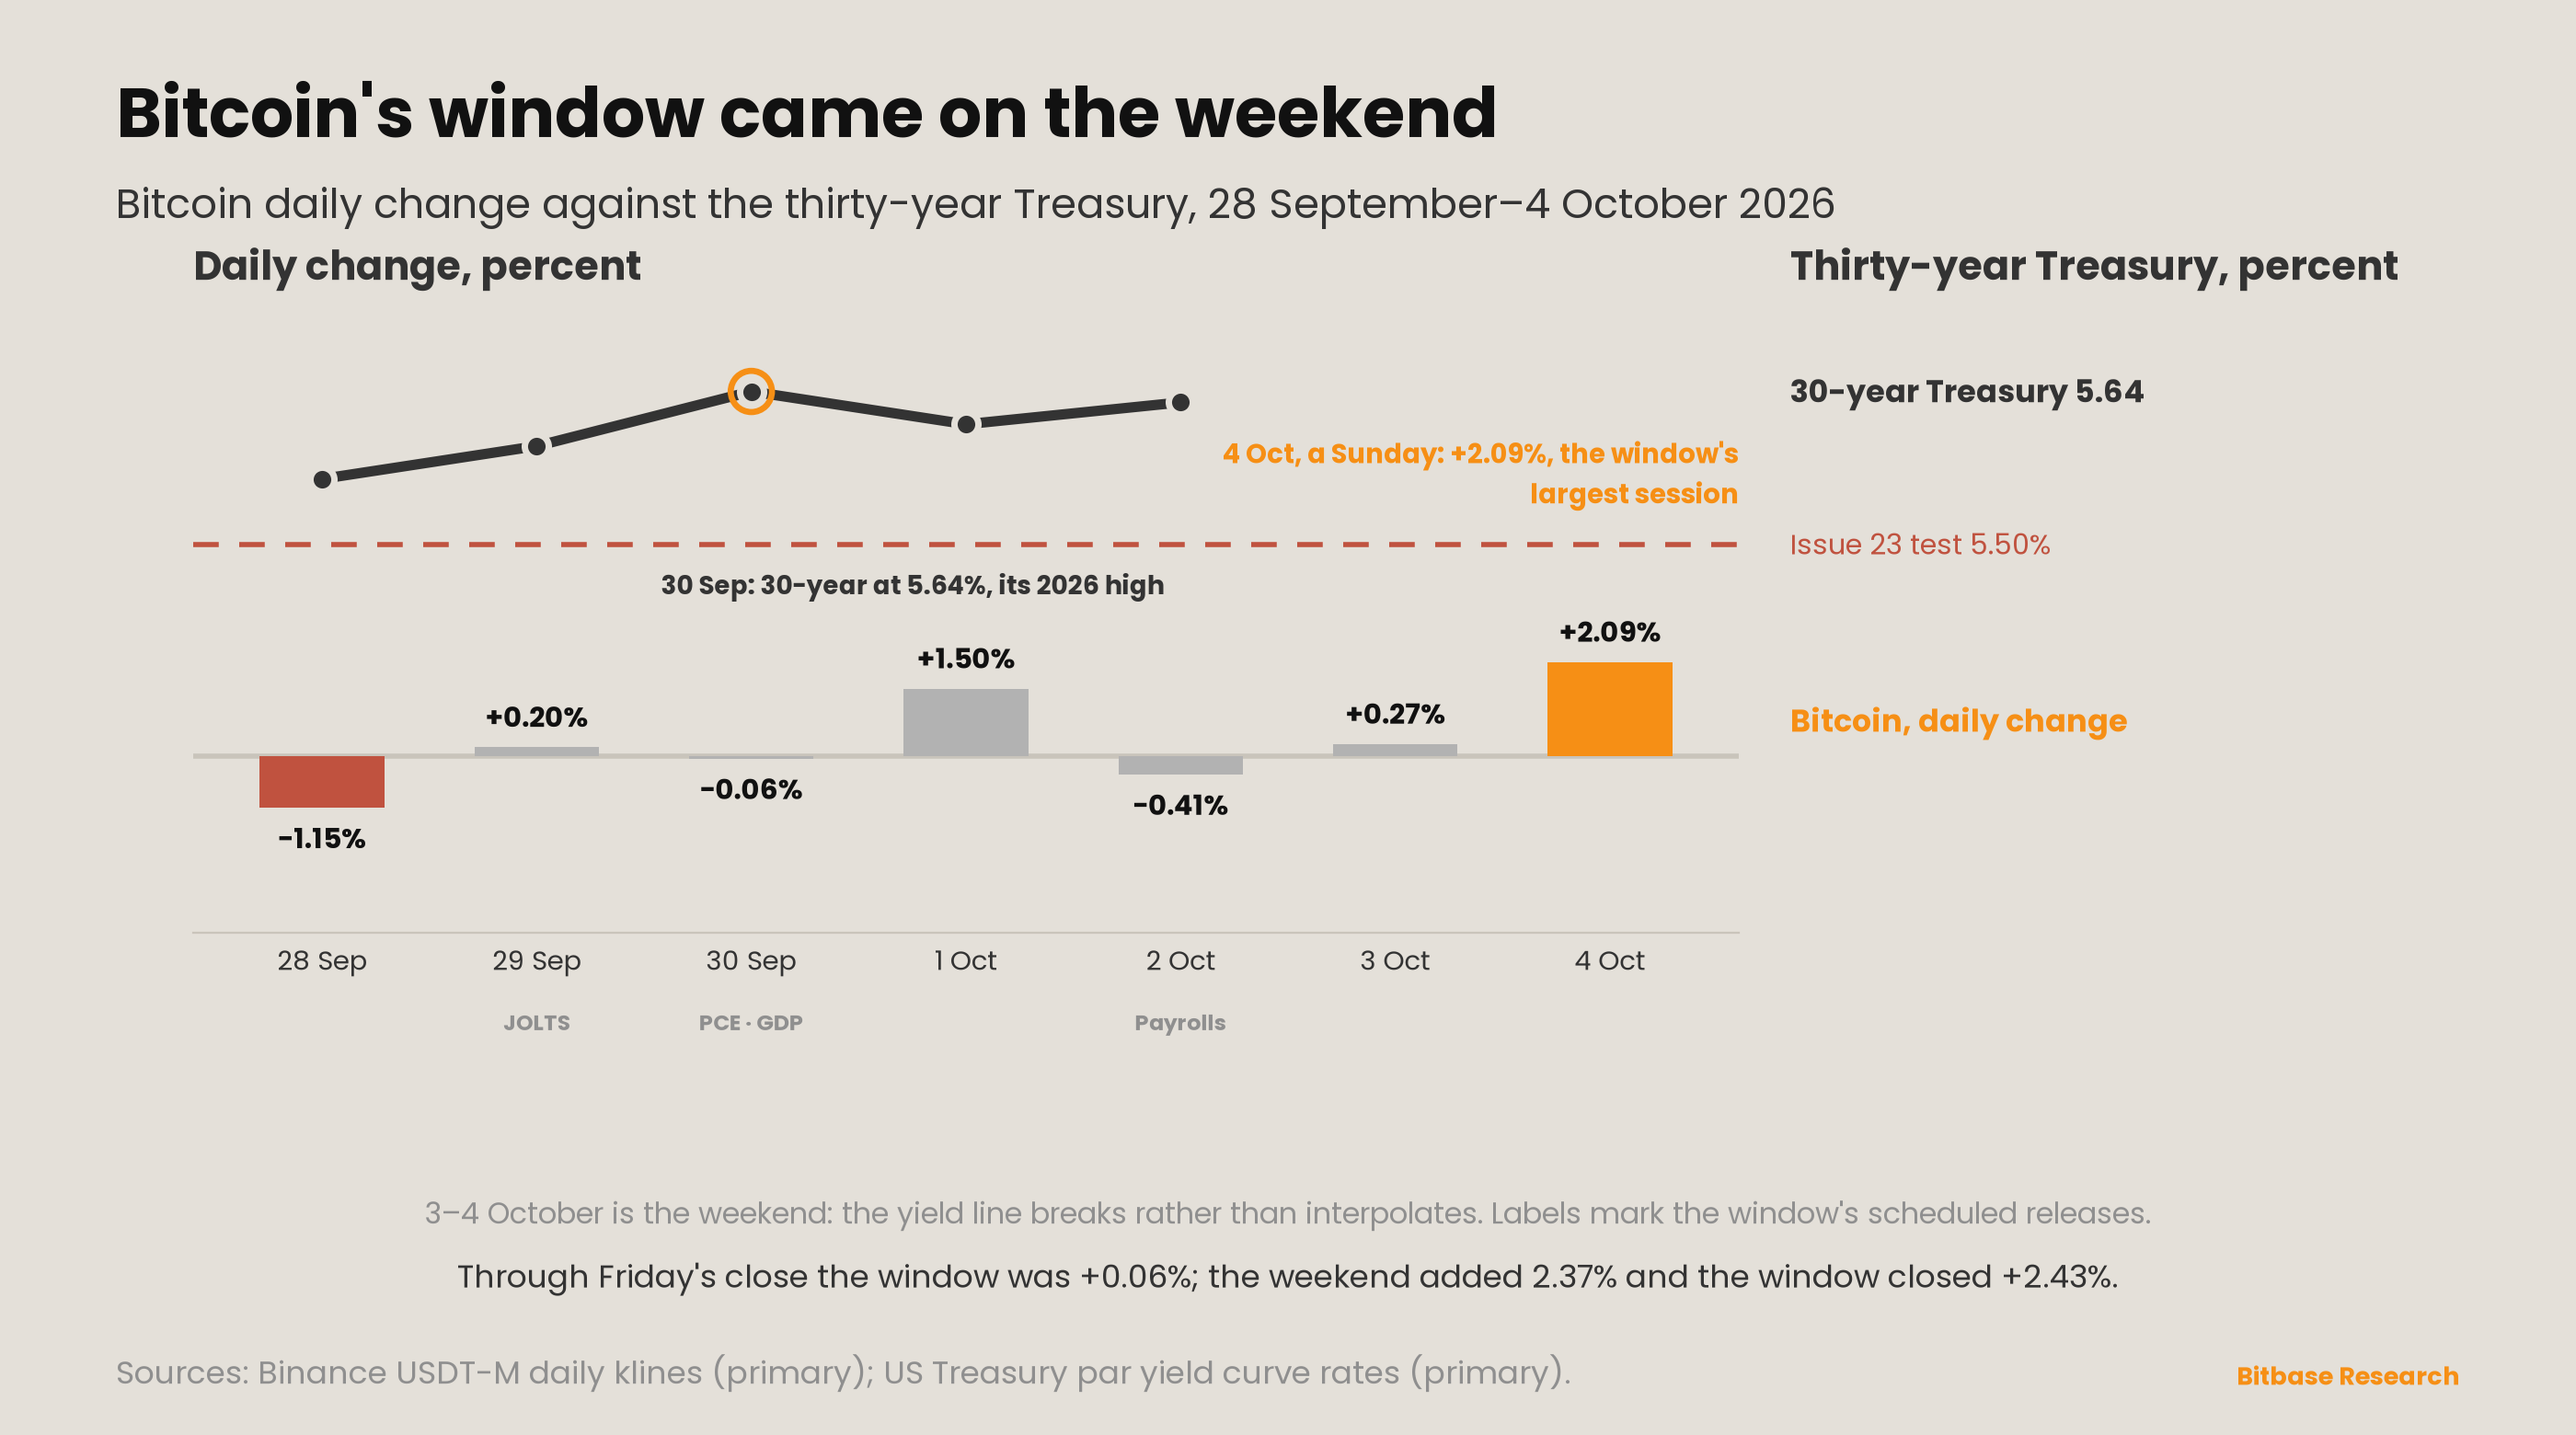
Daily closes for BTCUSDT perpetuals, USDT-margined futures, UTC, with the thirty-year Treasury par yield on the right axis and Issue 23's 5.50% line marked [2][3]:
| Date (UTC) | Close | Session | Release | 30Y par yield |
|---|---|---|---|---|
| September 27 (prior close) | 84,432.90 | +0.04% | — | — |
| September 28 | 83,461.00 | −1.15% | — | 5.56 |
| September 29 | 83,624.50 | +0.20% | JOLTS | 5.59 |
| September 30 | 83,576.90 | −0.06% | PCE, GDP | 5.64 |
| October 1 | 84,829.60 | +1.50% | — | 5.61 |
| October 2 | 84,482.80 | −0.41% | Payrolls | 5.63 |
| October 3 | 84,710.60 | +0.27% | — | — |
| October 4 | 86,482.80 | +2.09% | — | — |
Through Friday's close the window had gone almost nowhere [3]. Five sessions that carried JOLTS, the PCE report, the GDP revision and the payroll report left the contract 0.06% above the prior close, on our arithmetic, after a low of 82,500.10 on the first of them. Saturday added 0.27% and Sunday 2.09%, the largest Sunday gain since June 7, and the window closed at 86,482.80, +2.43%. The two weekend sessions were the two with the least volume traded in the contract, 43,166 and 66,983 bitcoin, against a weekday range of 123,045 to 232,091.
The PCE day and the payroll day both printed their highs around the release and closed below them [3][8][10]. On September 30, when the PCE report and the GDP revision were published at 12:30 UTC, the session's high of 85,632.70 came in the 13:00 UTC hour, and the session closed 2.40% below it. On October 2, the payroll day, the window's high of 87,249.60 came in the 12:00 UTC hour, and the close was 3.17% below it. In both sessions the close was lower than the price at which the 12:00 UTC hour opened. This is a description of timing on two days, not a finding about how bitcoin responds to data; section 7 says why two days cannot carry more.
The right-hand axis cleared Issue 23's line on the first session and stayed above it [2]. The thirty-year closed at 5.56% on September 28, at 5.64% on September 30, its highest reading of 2026, and at 5.63% on October 2. The two markets did not share their large sessions: the thirty-year's largest daily rise, 7 basis points, came on September 28, when bitcoin closed −1.15%, and bitcoin's largest gain came on a Sunday, when the Treasury market was shut. That is an observation about timing, not a claim that the two are unrelated.
This week's structural signal
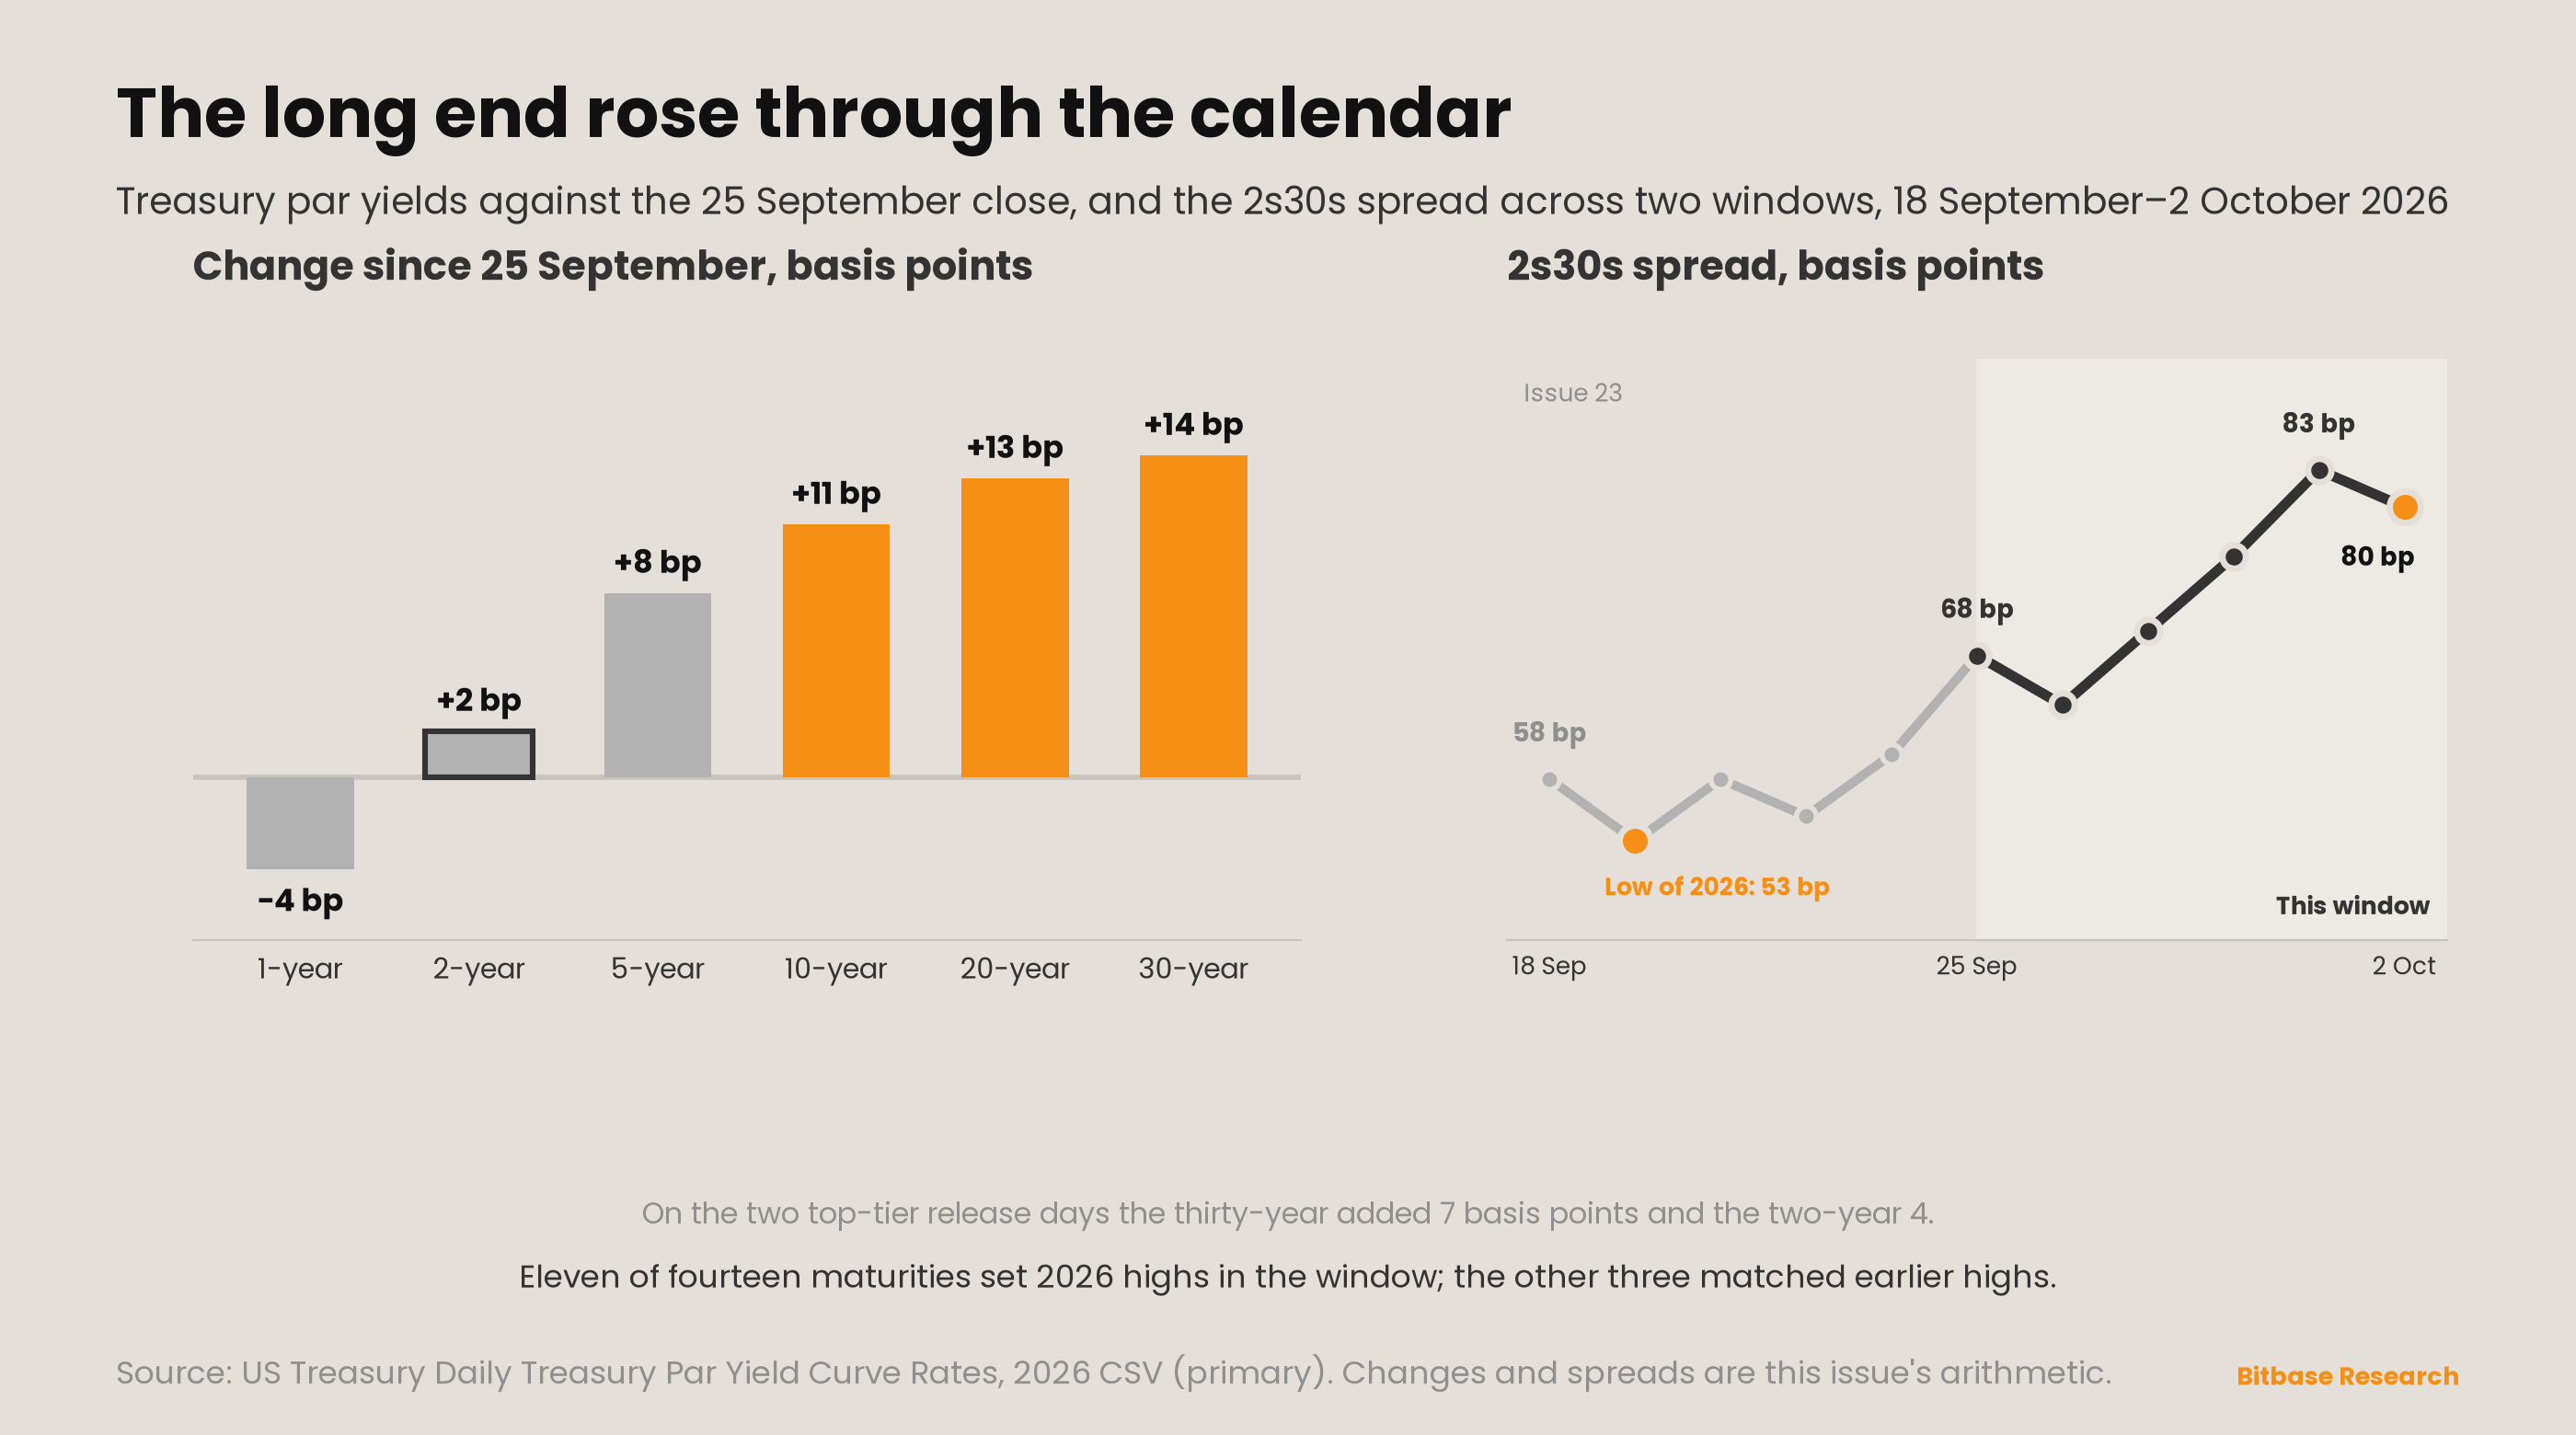
Change against the prior close of September 25, in basis points [2]:
| 1Y | 2Y | 5Y | 10Y | 20Y | 30Y |
|---|---|---|---|---|---|
| −4 | +2 | +8 | +11 | +13 | +14 |
For a second window the long end did the moving, and this time it had a calendar to move on [2][8][9][10][11]. Issue 23 recorded a thirty-year that rose 15 basis points in a week with no FOMC meeting and no top-tier release, and noted that the next window would bring a full calendar. It added 14 more. The two-year ended the window 2 basis points higher and the one-year 4 lower. A curve whose front end is flat to lower while its long end rises is steepening from the back, and the 2s30s spread widened from 68 basis points to 80, after 83 on October 1.
| 09-25 (prior close) | 09-28 | 09-29 | 09-30 | 10-01 | 10-02 | |
|---|---|---|---|---|---|---|
| 2Y | 4.81 | 4.92 | 4.89 | 4.88 | 4.78 | 4.83 |
| 10Y | 5.17 | 5.24 | 5.26 | 5.29 | 5.24 | 5.28 |
| 30Y | 5.49 | 5.56 | 5.59 | 5.64 | 5.61 | 5.63 |
| 2s10s | 36bp | 32bp | 37bp | 41bp | 46bp | 45bp |
| 2s30s | 68bp | 64bp | 70bp | 76bp | 83bp | 80bp |
The two top-tier release days carried half of the long-end move, and the two-year's largest moves fell on neither [2]. On our arithmetic, across the two sessions that carried a top-tier release — the PCE report and the GDP revision on September 30, the payroll report on October 2 — the thirty-year added 7 of its 14 basis points and the two-year 4, more than its net change for the window. The two-year's two largest moves came on sessions without one: +11 basis points on September 28, to 4.92%, its high of 2026, and −10 on October 1. JOLTS, on September 29, sits outside the top tier as this series defines it; that day the thirty-year added 3 and the two-year lost 3. What moved the front end did not arrive on the calendar this series reads, and this issue does not name what did.
The releases themselves, as published [8][9][10]. The August PCE price index rose 0.3% on the month and 3.4% on the year; excluding food and energy, 0.2% and 3.0%. Real GDP for the second quarter was revised up 0.7 percentage point, to an annual rate of 2.2%. September payrolls rose 29,000, the unemployment rate was 4.2%, and July and August combined were revised down by 60,000. On the payroll day the two-year rose 5 basis points and the thirty-year 2. A payroll gain of 29,000 with 60,000 revised away, and a two-year that rose on the day, is a pairing this issue records without explaining.
Eleven of the fourteen maturities in the Treasury's table set new highs for 2026, and the other three matched earlier highs [2]. The two-year made its high on the first session; the five-year through the thirty-year made theirs on September 30, the PCE day. The 2s30s spread has widened by 27 basis points in the nine sessions since its 2026 low of 53 on September 21, and remains far below its 2026 high of 139 on January 6. The structural reading carries over from Issue 23, unchanged in kind and now two windows long: a bear steepening, led from the back, that the data here cannot attribute to a delayed response to the September projections, to a larger premium for holding duration, or to supply.
Dual-track scoreboard
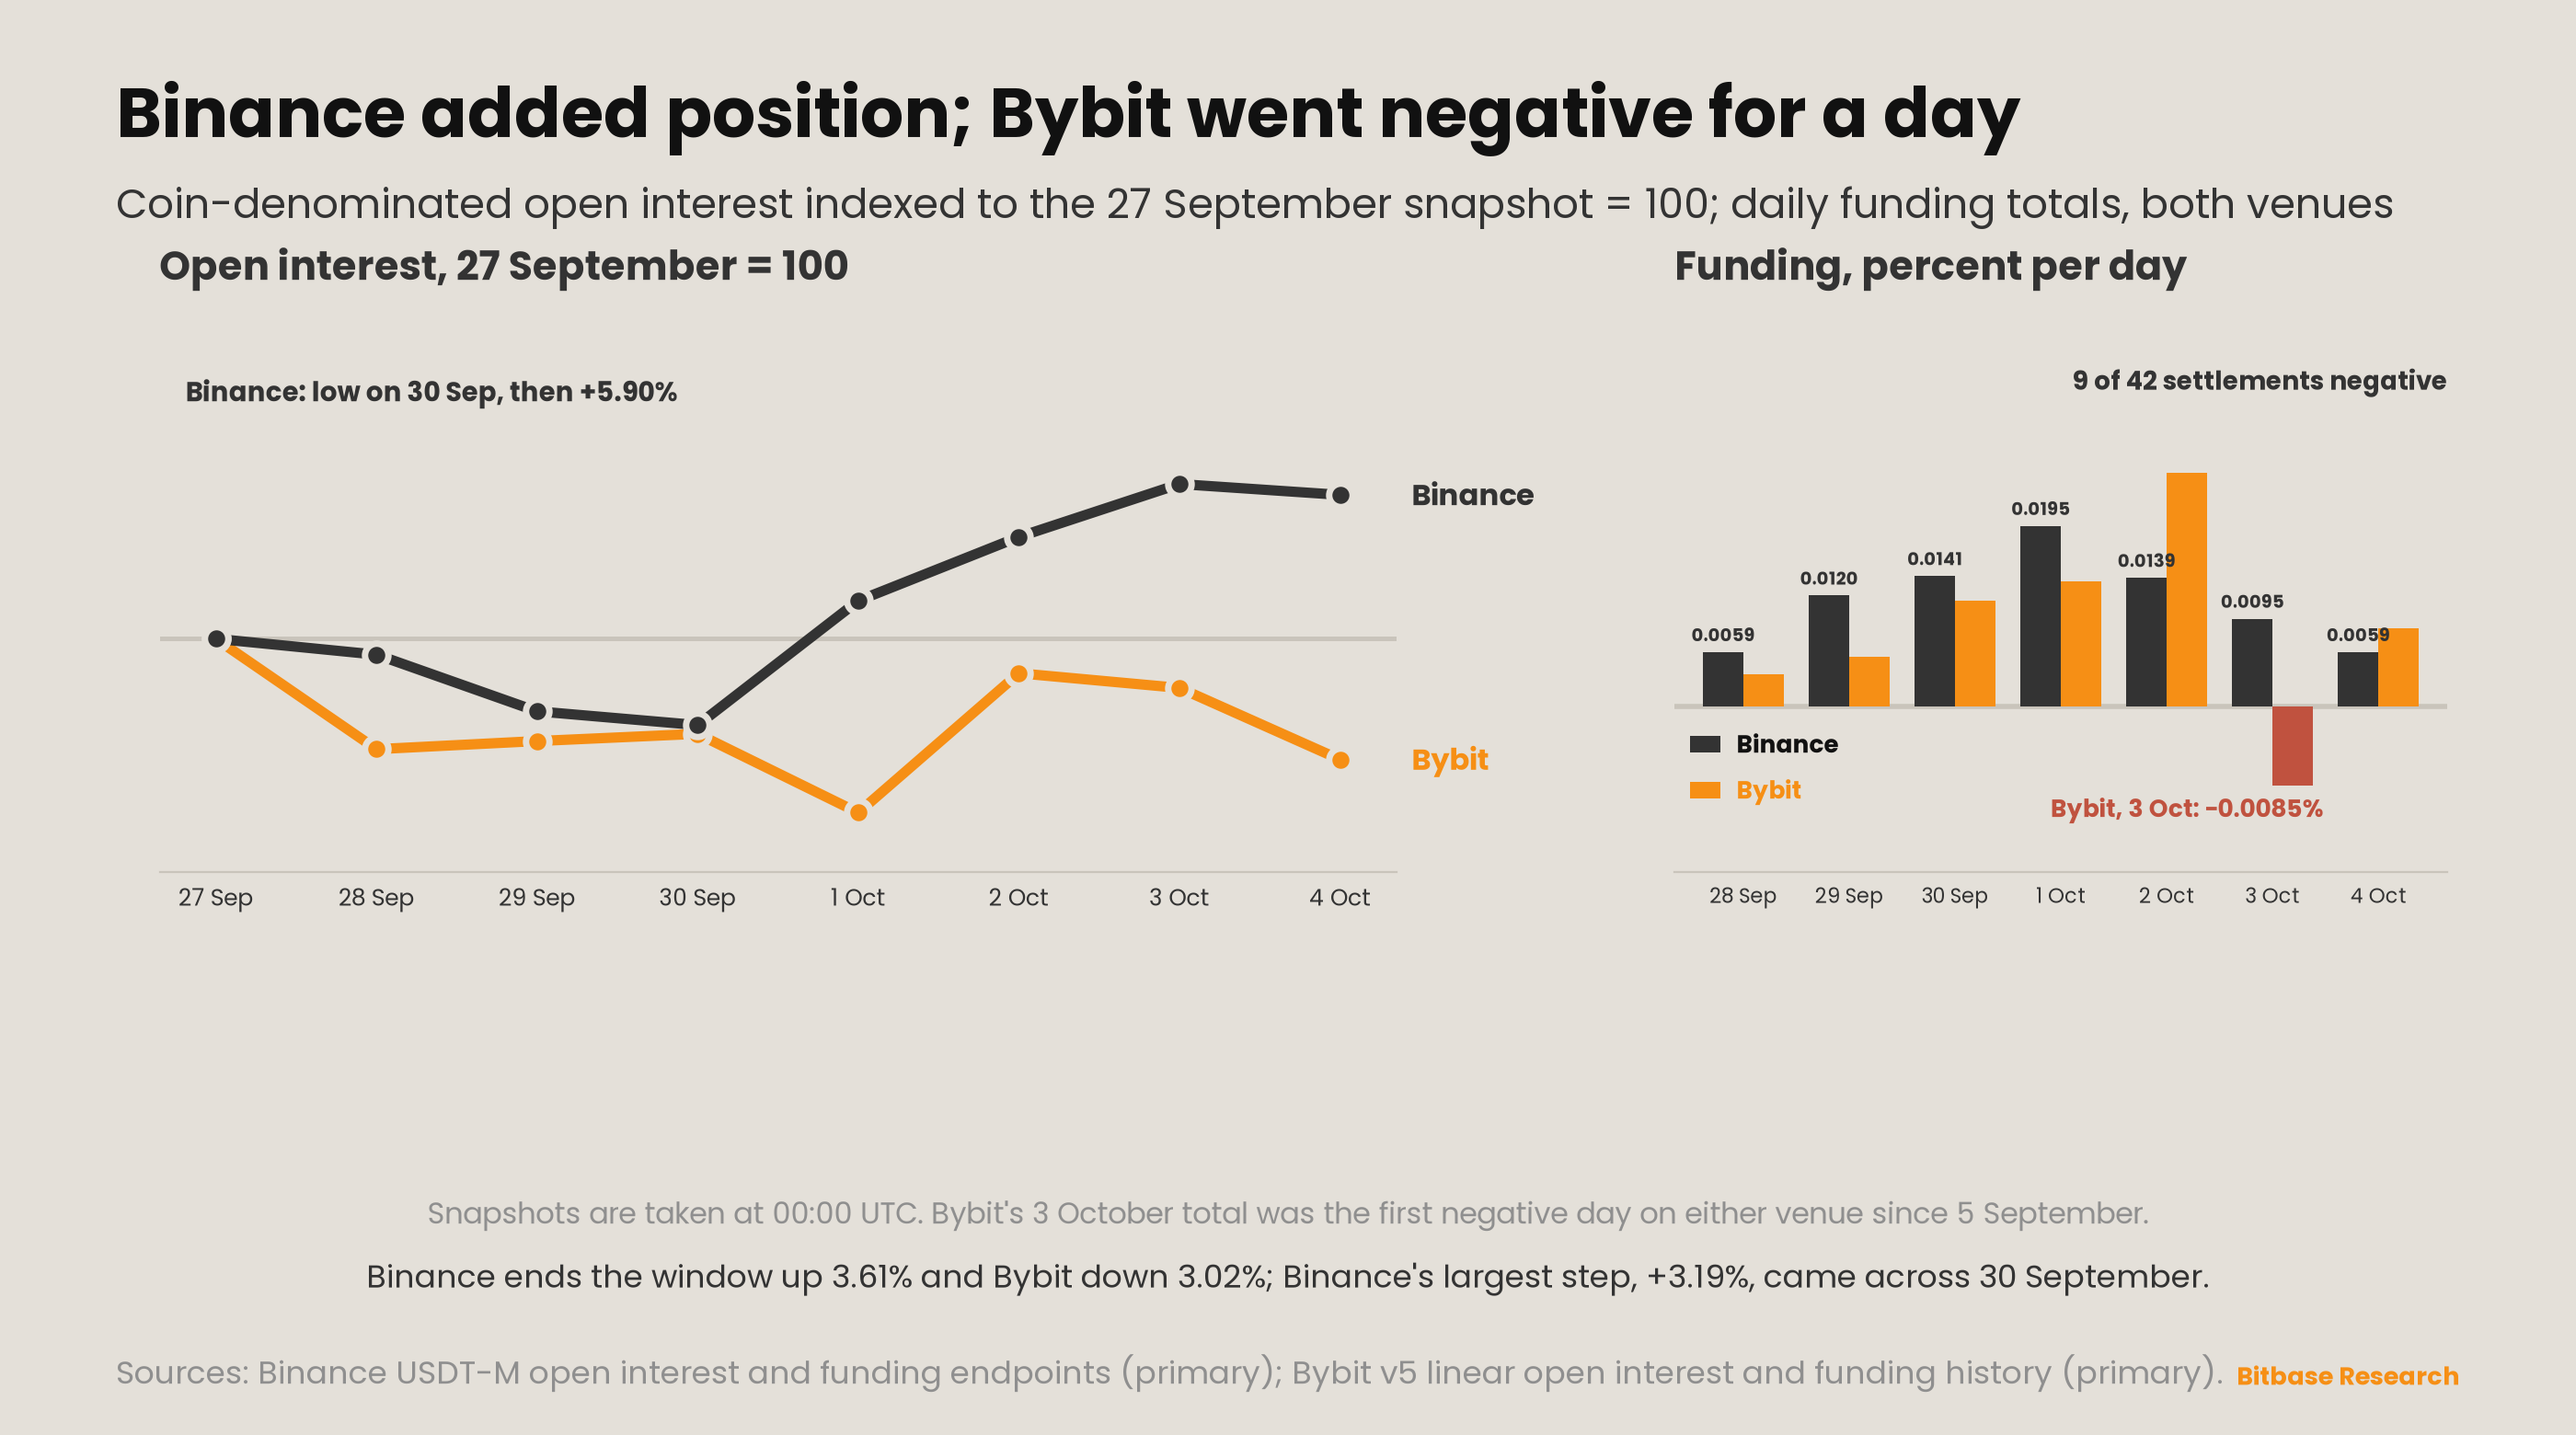
Coin-denominated open interest in BTCUSDT perpetuals, daily snapshots at 00:00 UTC [4][6]:
| Snapshot (00:00 UTC) | Binance (BTC) | Bybit (BTC) |
|---|---|---|
| September 27 (prior close) | 94,518 | 56,970 |
| September 28 | 94,143 | 55,394 |
| September 29 | 92,800 | 55,510 |
| September 30 | 92,474 | 55,613 |
| October 1 | 95,419 | 54,488 |
| October 2 | 96,931 | 56,478 |
| October 3 | 98,184 | 56,269 |
| October 4 | 97,928 | 55,247 |
Binance ends the window up 3.61%; Bybit down 3.02% [4][6]. The venues split for a second window, in the opposite direction: in Issue 23 Binance fell and Bybit ended slightly higher. Binance open interest fell across the first three snapshots to 92,474 and then rose 5.90% to the end of the window; its largest step, +3.19%, came between the snapshots either side of September 30, the session that carried the PCE report. Bybit's low came a snapshot later, and its largest step, +3.65%, came across October 1. Because it is measured in coins rather than dollars, each step is a count of contracts opened or closed, not a revaluation — and it says nothing about which side opened them.
Funding, summed across the three eight-hour settlements in each UTC day; window totals are summed from the unrounded settlements [5][7]:
| Date | Binance | Bybit |
|---|---|---|
| September 28 | +0.0059% | +0.0035% |
| September 29 | +0.0120% | +0.0054% |
| September 30 | +0.0141% | +0.0114% |
| October 1 | +0.0195% | +0.0135% |
| October 2 | +0.0139% | +0.0252% |
| October 3 | +0.0095% | −0.0085% |
| October 4 | +0.0059% | +0.0085% |
| Window total | +0.0808% | +0.0589% |
On Saturday, October 3, all three Bybit settlements were negative, and the day summed to −0.0085% [7]. It is the first negative daily total on either venue since September 5. Binance did not print one: its three negative settlements, on September 28, September 30 and October 4, were each outweighed within the day [5]. Nine of the forty-two settlements were negative, against six in Issue 23. On our arithmetic the window totals were 125% of Issue 23's on Binance and 70% on Bybit. The venues disagreed on direction as well as on size: longs on Binance paid more than a week earlier, longs on Bybit paid less, and for one day they were paid.
What is absent from this scoreboard, and named rather than omitted: spot ETF daily flows, for the reason recorded in Issues 21 to 23 — this series has no primary retrieval path for them and does not source them second-hand.
On the radar—week of October 5 to October 11
First, what does the filing covering this window fund, and with what? As of this issue's data cut, 09:25 UTC on October 5, the filing does not exist: the most recent Form 8-K on the company's EDGAR index is the October 1 filing on Stretch dividends [15]. The last five purchase disclosures read 4,603 bitcoin, zero, zero, 950 and 1,665 — the first and the last funded by share sales, the 950 by USD Cash [1][16][17]. The next one either stays with share sales, returns to USD Cash, or buys nothing.
Second, does USD Cash print $0.99bn or lower? It printed $1.00bn as of September 27 [1]. Issue 23 asked whether it would fall below $1.00bn, and a balance disclosed to two decimal places cannot answer that while it reads $1.00bn; the question is restated at the precision of the disclosure, and section 5 explains why.
Third, does the thirty-year stay above 5.50% on every session of a week without a top-tier release? It closed the window at 5.63% [2]. The next window has no FOMC meeting, no release on the Bureau of Labor Statistics schedule between October 5 and 9, and no GDP or PCE release, which the Bureau of Economic Analysis has on October 29; the September CPI is scheduled for October 14 [18][19][21]. Issue 23's long end rose on an empty calendar and this one rose through a full one; the next window shows whether the level holds on an empty one again.
Fourth, does Binance print a negative daily funding total? Bybit did on October 3; Binance printed three negative settlements and no negative day [5][7]. It is decidable from the same endpoint, and it would make the negative day a reading on two venues rather than one.
Fifth, does another GENIUS Act rulemaking document reach the Federal Register? Three were published in this window [12][13][14]. The same Federal Register query this issue ran will answer it, and this series will report the documents and their dates, not their contents, until there is a final rule.
Signal tracking update
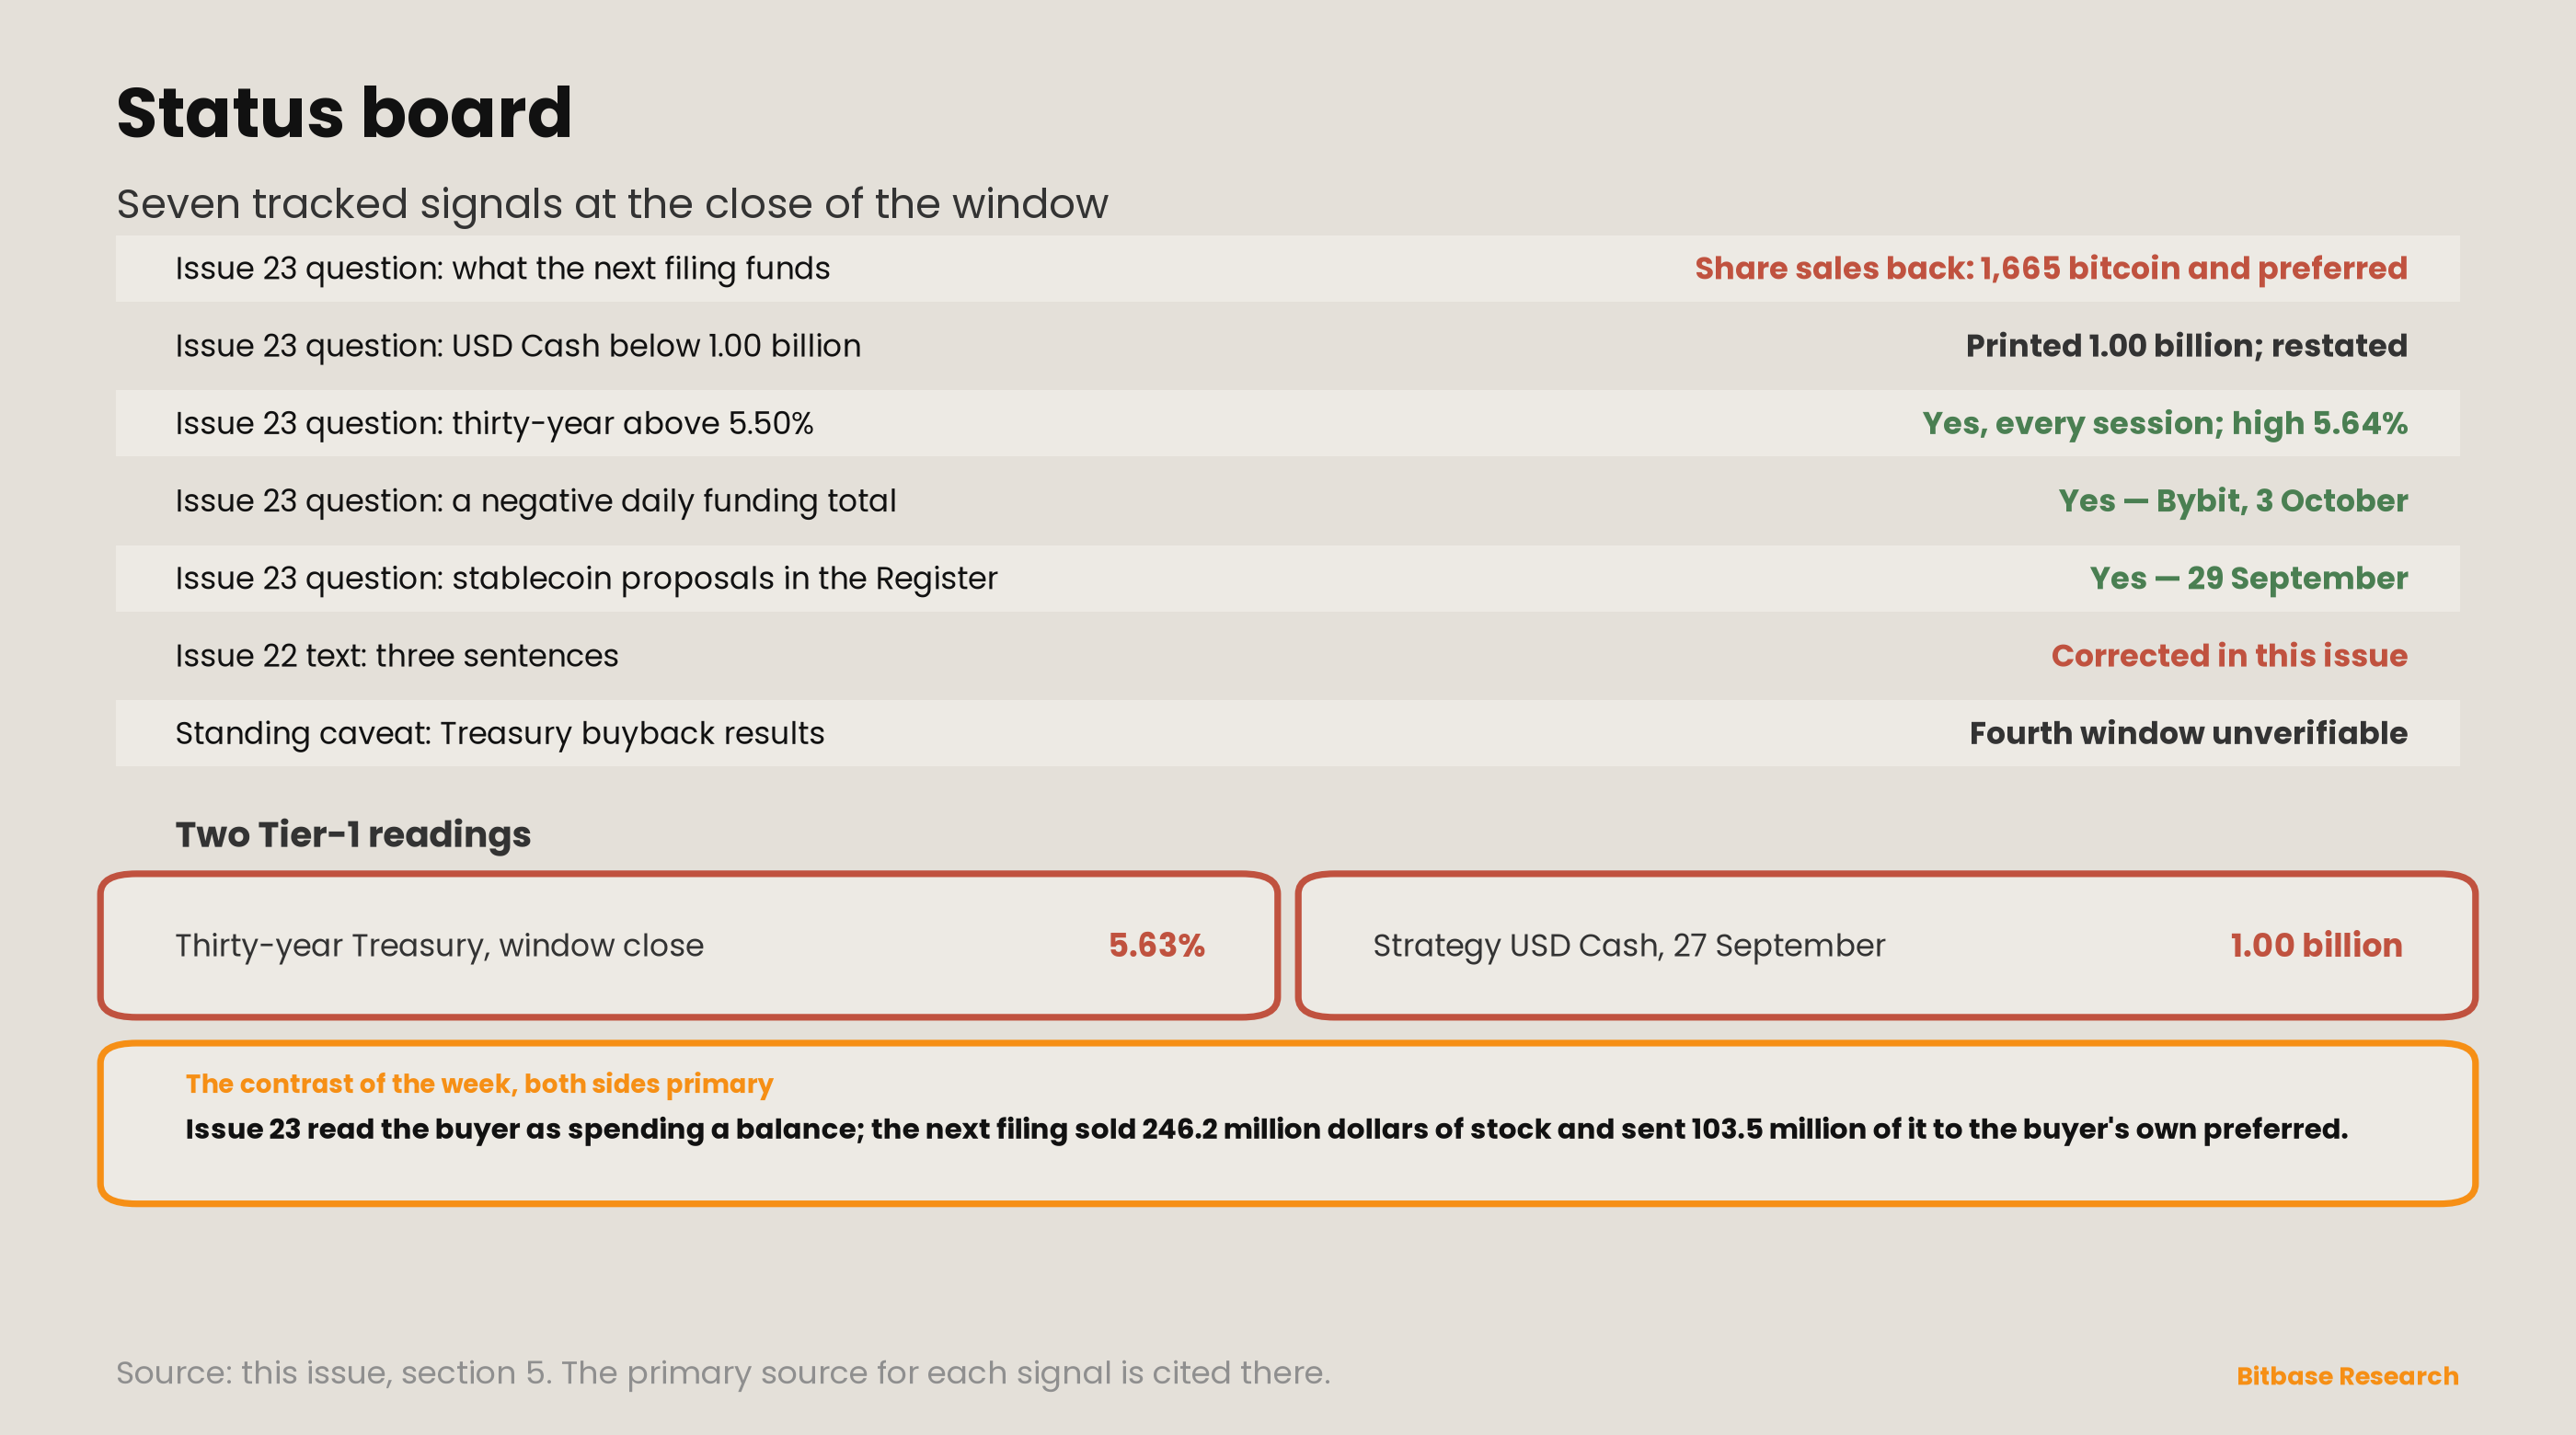
Issue 23's radar asked five questions. Four settle; one cannot be settled at the precision of its own data and is restated. After them, three sentences of Issue 22 are corrected on the record.
First, what does the filing covering Issue 23's window fund, and from which account? Bitcoin and the company's own preferred, mostly from share sales [1]. The filing for September 21 to 27 records 1,469,165 shares of common stock sold for net proceeds of $246.2m, the first at-the-market sales since the filing covering August 24 to 30. It states the split: $142.7m to 1,665 bitcoin at an average of $85,681 including fees, and $103.5m to repurchases of Strategy's Stretch preferred. A further $48.1m of USD Cash went to the same repurchases, which came to 1,534,530 shares for $151.7m. On our arithmetic, 58.0% of the share-sale proceeds bought bitcoin and 42.0% bought back preferred. Holdings as of September 27 were 847,666 bitcoin at an aggregate $63.95bn and an average of $75,437. Issue 23 named this possibility — one filing could restore the previous pattern — and one filing did. One clarification belongs beside it: Issue 23 described that pattern as selling stock to buy bitcoin, but the filing covering August 24 to 30 had also sent $151.8m of share-sale proceeds to Stretch repurchases [16]. The pattern that returned is that one: stock sold, and both bitcoin and preferred bought with it.
Second, did USD Cash fall below $1.00bn? The filing prints $1.00bn, which at two decimal places is the line itself [1][17]. On our arithmetic, the $1.05bn of September 20 less the $48.1m drawn is $1.0019bn, but both balances are rounded to the nearest $0.01bn, so the true figure could sit up to $5m on either side of the line. The question was asked at a precision the disclosure does not have. STATUS: CHANGED SHAPE. Section 4 restates it as a question the disclosure can decide. What sat behind the question changed as well: USD Cash paid $48.1m in this filing, against $249.7m in the filing before.
Third, did the thirty-year close above 5.50%? Yes, on every session, from the first [2]. Readings 5.56, 5.59, 5.64, 5.61, 5.63; the 5.64% of September 30 is its high of 2026. STATUS: CONFIRMED. A threshold crossed on the first session and held for five is a level rather than a test, so section 4 asks instead whether the level holds through a week without a top-tier release.
Fourth, did either venue print a negative daily funding total? Yes — Bybit, on October 3, at −0.0085% [7]. All three of its settlements that day were negative; Binance printed no negative day [5]. Issue 23 called a negative day the next step in the direction its six negative settlements pointed. The step came on one venue, on a Saturday, and the question is settled on the measure it was asked on; the two-venue version moves to section 4.
Fifth, did the Federal Reserve's stablecoin proposals reach the Federal Register? Yes, both, on September 29; comments close on November 30 [12][13]. Issue 23 said this series would report the date the clock starts rather than read the proposals. That date is September 29, and section 6 sets it beside the other dates now on the record.
Three sentences in Issue 22 are corrected here, as Issue 23 corrected the filing that Issue 22 attached to the wrong week. None of them changes a number in Issue 22's tables; each changes what a sentence said about those numbers.
First, Issue 22's lead said that open interest and funding "both rose the whole way, on both venues", and its chart 3 title said the same in other words. They did not [4][5][6][7]. Across the seven daily steps of that window, Binance open interest fell in three and Bybit's in three; Binance's daily funding total fell on one day and Bybit's on two. What holds is narrower: both venues ended the window with more open interest than they began it with, Binance 4.21% more and Bybit 6.38%, and all 42 settlements were positive.
Second, Issue 22's section 6 listed "shorts being forced" among the readings compatible with open interest rising alongside price. It is not one. A short that is forced to close takes a contract out of the book, so forced covering lowers open interest and cannot by itself produce a rise. Of the three readings, only new longs and spot holders hedging with short perpetuals add contracts, and the later sentence in which "forced shorts" print the same series falls with it.
Third, Issue 22's section 7 said that a summarising fetch "had shifted one column". It had not shifted the table [2]. The same paragraph said that the ten-year matched to the digit, which a shifted table would not have done. What the fetch did was narrower: it returned the one-year's 4.44 in the two-year's place and the twenty-year's 5.38 in the thirty-year's, two columns read as their neighbours, with the ten-year's 5.01 untouched. The check Issue 22 described stands; its description of what the check caught was too broad.
New dimension—the stablecoin law now runs on dates
Issue 23 recorded the Federal Reserve's request for comment on two proposals under the GENIUS Act and said this series would not read them before there is a final rule. This window put the law's implementation into dated documents, and the dates are what this section reads.
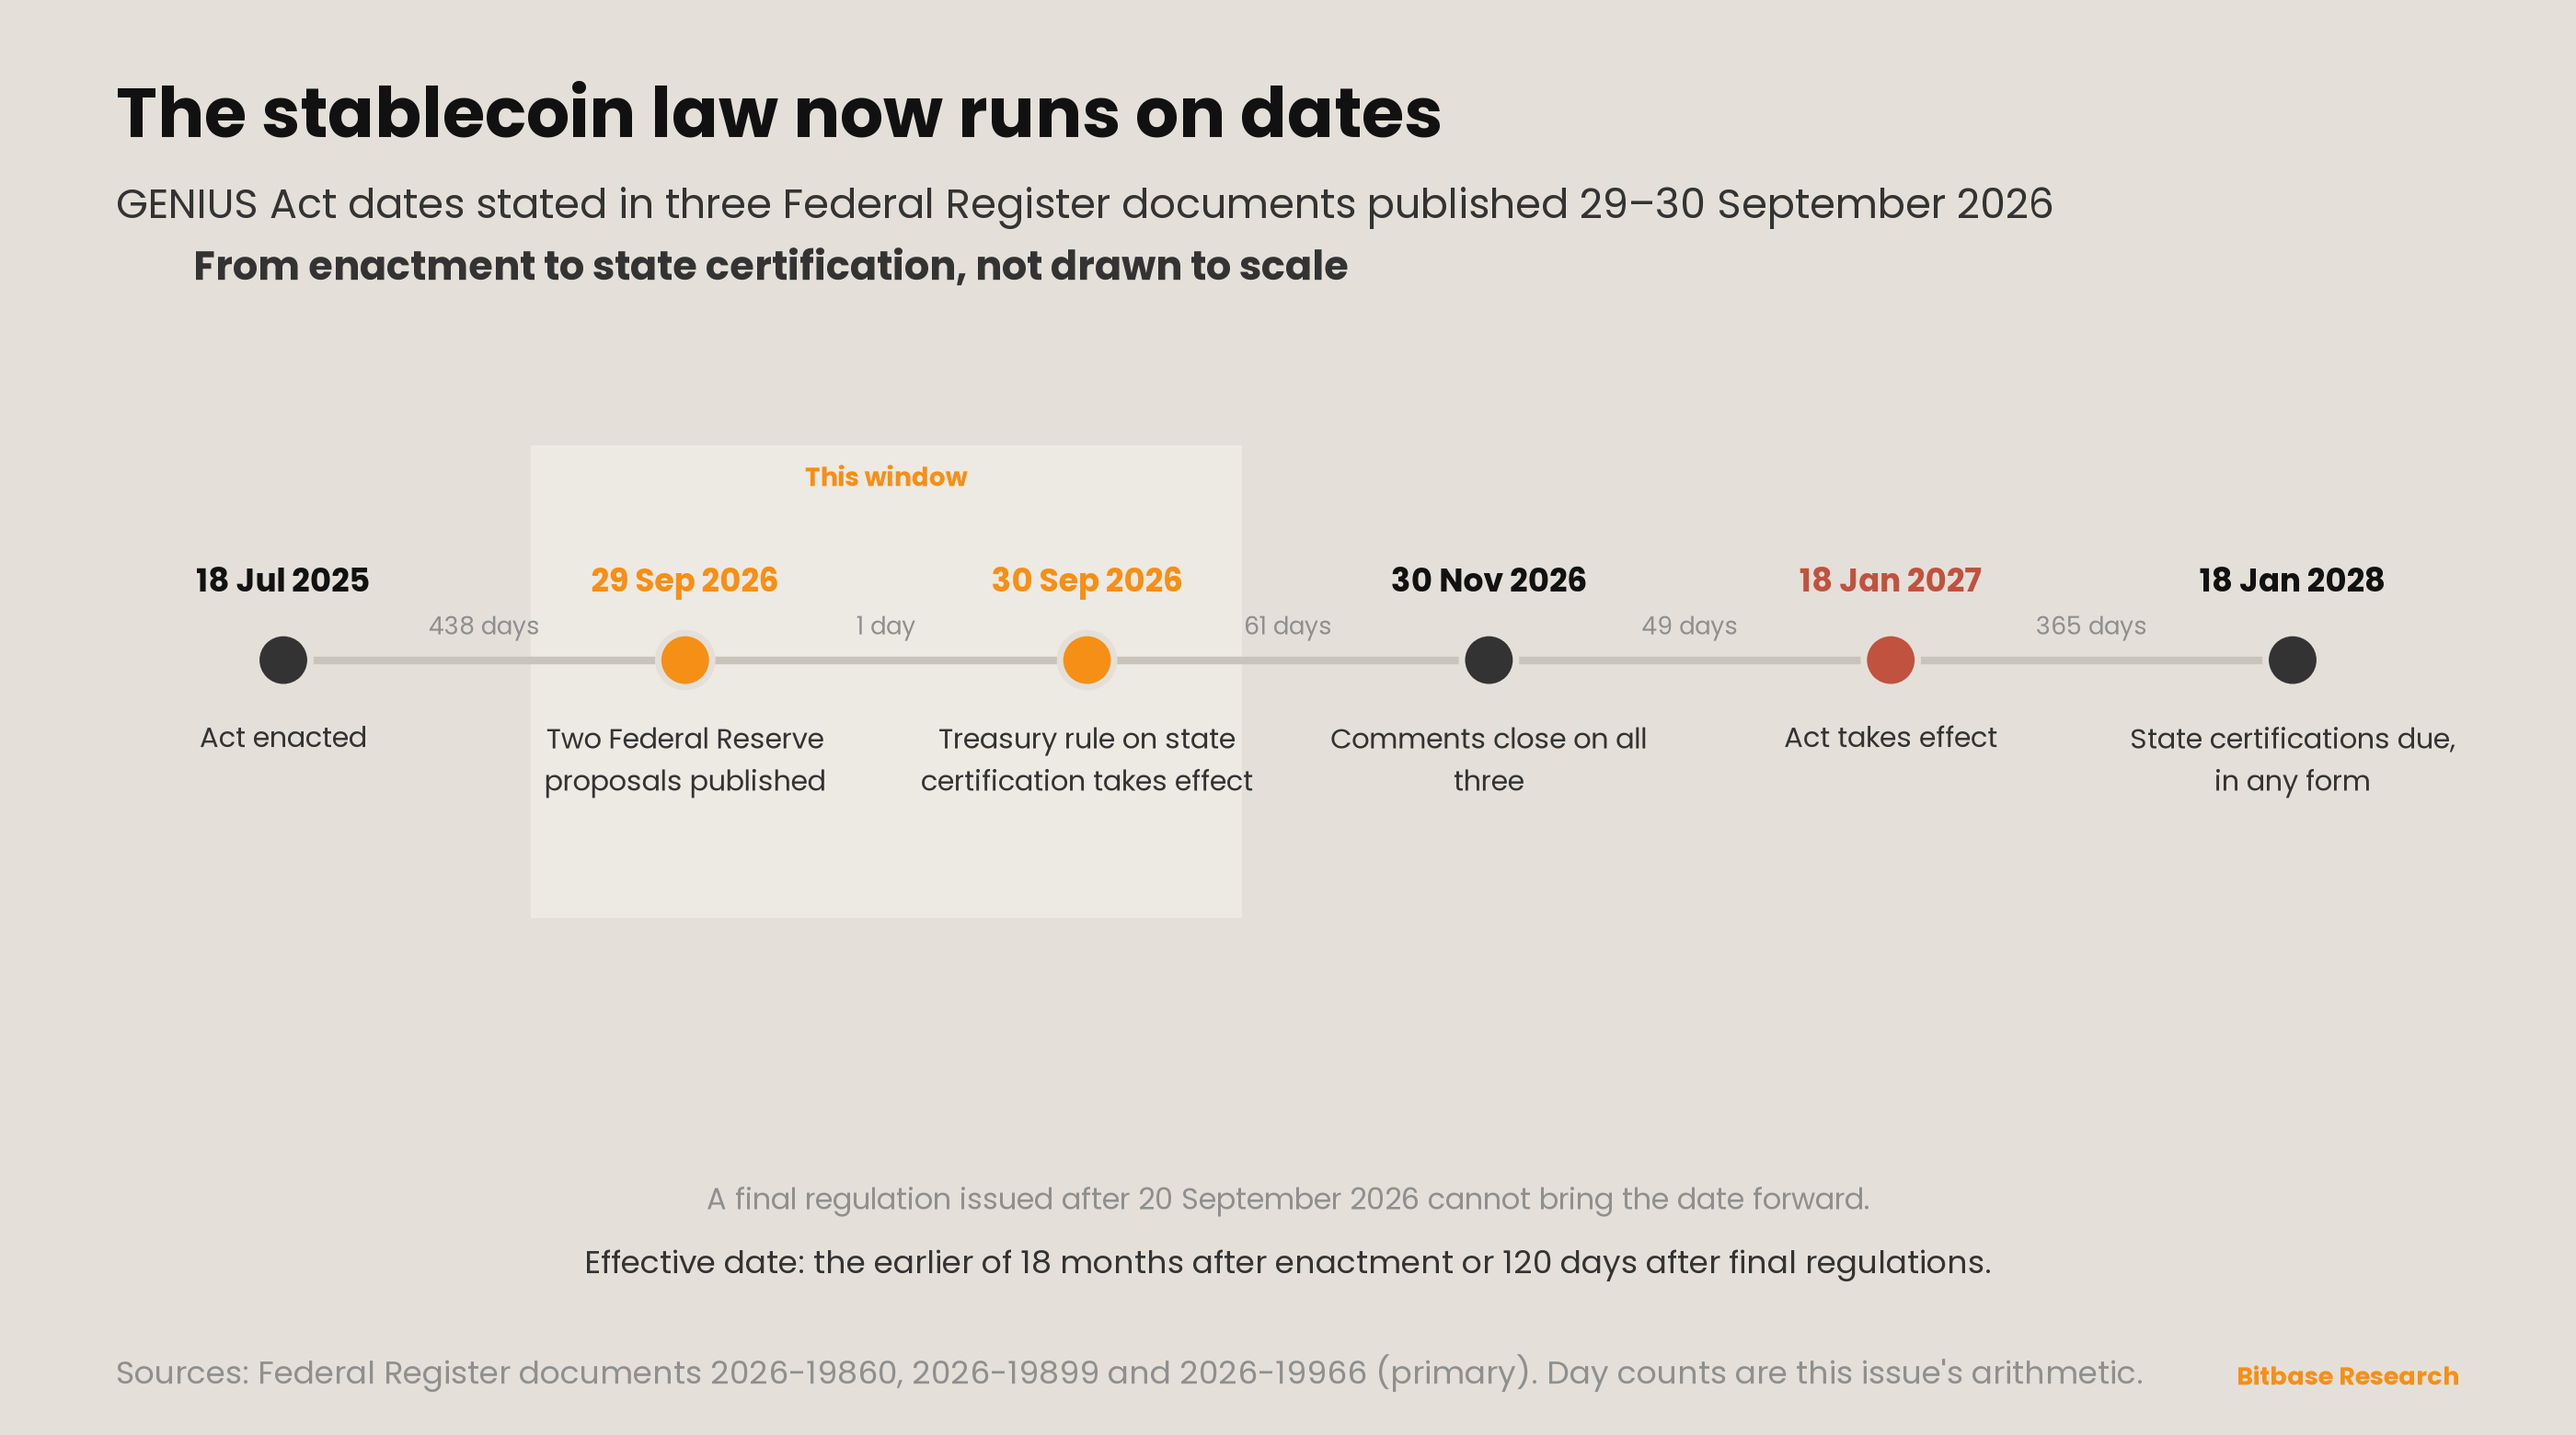
Three documents reached the Federal Register in two days [12][13][14]. On September 29 it published both Federal Reserve proposals: one implementing the Board's responsibilities under the Act for the payment stablecoin issuers it supervises, 104 pages, and one setting the procedure by which insured state member banks apply for approval for a subsidiary to issue payment stablecoins, 16 pages. Comments on both are due by November 30, 2026. On September 30 it published an interim final rule from Treasury, issued on behalf of the Stablecoin Certification Review Committee, setting the forms and procedures by which state payment stablecoin regulators certify their regimes. It took effect on publication, but certifications will not be accepted until the information collection is approved under the Paperwork Reduction Act. Comments on it are also due by November 30.
Two of the documents state the date that governs the rest [13][14]. The Federal Reserve's application proposal says that the Act's effective date "is the earlier of 18 months after the enactment date of July 18, 2025, or 120 days after the primary Federal payment stablecoin regulators issue any final regulations implementing the Act". Treasury's rule names it: "the GENIUS Act takes effect on January 18, 2027, at which time it will generally be unlawful for persons to issue payment stablecoins in the United States unless they are licensed or approved as permitted payment stablecoin issuers".
On our arithmetic, the comment periods close 49 days before that date. A final regulation issued after September 20, 2026 would put the 120-day branch later than January 18, 2027, so no rule issued from this window on can bring the date forward. What lies between the close of comment and the date the Act takes effect is seven weeks.
Treasury's rule also says why it did not wait [14]. Many current payment stablecoin issuers are licensed and regulated at the state level, it notes, and failing to have certification procedures in place by the effective date "could impede the ability of issuers to continue normal issuance operations or create significant market uncertainty, potentially causing dislocation in the multi-billion-dollar stablecoin market in the United States". It also says that a state regulator would, at a minimum, satisfy the Act's initial-certification requirement by submitting any form of certification by January 18, 2028, including one that is conditional on further state work. In that sentence the market this series covers appears as a risk the rule is meant to avoid, not as a forecast.
What this does not establish. It does not establish what the final rules will require; this series has not read the substance of the proposals and will not until there is a final rule. It does not establish that the January date is beyond change, since it rests on the Act's text as the agencies state it rather than on a reading of the Act here. It says nothing about stablecoin supply, which this series does not track. What it establishes is a calendar: comments by November 30, 2026, the Act in effect on January 18, 2027, and state certifications by January 18, 2028, each stated in a primary document and each a date on which a later issue can check what happened.
Caveats
Section 1's weekday–weekend split describes one window, not a pattern. Seven sessions cannot show that bitcoin moves at weekends or that it ignores data, and the two release-day highs are two observations, not a response function. The weekend sessions were also the two thinnest in the contract, so the window's gain was made on its least-traded days; this issue records that as a fact about volume, not as a judgement about the move.
Section 2's release-day accounting is arithmetic, not attribution. Summing changes by calendar day assigns a move to the day it happened on, not to the release published that day; other data, auctions, moves in other sovereign markets and positioning all fall on the same days. The two-year's largest moves came on days that this series' calendar marks as empty, which is a statement about the calendar's coverage as much as about the market.
The auction calendar remains the blind spot. Treasury publishes auction results on the host whose certificate chain does not verify on this machine, so this issue does not know which coupon auctions fell inside the window or how they cleared. Supply is one of the explanations for a rising long end that section 2 cannot exclude, and this issue says so rather than writing as if the week carried none.
Section 3's open interest counts contracts, not intentions. A rise on Binance and a fall on Bybit are compatible with positions moving between venues, with different participants on each, and with both; coin-denominated open interest cannot separate them. The negative day is small — −0.0085%, on one venue and on a Saturday — and it is reported because it settles a question asked in advance, not because of its size.
Section 5's Strategy readings rest on the company's own allocation. The split of $246.2m between bitcoin and preferred is how the filing assigns the proceeds, not a tracing of cash, and the $1.00bn balance is rounded. No filing says why the company bought back preferred with the proceeds of common stock, and this issue does not supply a reason.
Section 5's corrections change sentences, not data. Every number in Issue 22's tables stands, and so does its reading of the curve. What changes is what three sentences claimed about those numbers; each correction quotes the words it replaces, so that it can be checked against Issue 22 itself.
Section 6 reads dates, not rules. The effective date and the deadlines are as the agencies state them in the Federal Register; this issue has not read the Act itself and does not assess what the proposals would require of any issuer.
One quantity remains a standing limitation. Treasury long-end buyback results: four windows, and in this one the same stated mode as the last — certificate chains that this machine's TLS library rejects on the TreasuryDirect and fiscal-data hosts, while the SEC's host verifies on the same path at the same time [20]. This is not evidence that no operation ran, and it will be restated each issue until the series has a verified retrieval path.
Related reading
Other Bitbase articles on this topic:
Disclaimer: This article is market commentary from Bitbase Research, provided for information only. The views are those of Bitbase Research as of the date of writing and do not constitute investment, trading, tax, or financial advice, nor an offer or solicitation to trade. Data in this issue is current as of October 4, 2026; markets and disclosures may change, so refer to the latest information from authoritative sources. Trading crypto assets and leveraged products carries significant risk, including the possible loss of your capital.
References
[1] Strategy Inc, Form 8-K filed September 28, 2026, accession 0001193125-26-403417, Item 8.01, period September 21–27, 2026. sec.gov
[2] US Treasury, Daily Treasury Par Yield Curve Rates, 2026 CSV download. home.treasury.gov
[3] Binance USDT-M futures, BTCUSDT klines, daily and hourly, UTC. fapi.binance.com
[4] Binance USDT-M futures, open interest history, BTCUSDT, daily. fapi.binance.com
[5] Binance USDT-M futures, funding rate history, BTCUSDT. fapi.binance.com
[6] Bybit, open interest, linear BTCUSDT, daily. api.bybit.com
[7] Bybit, funding rate history, linear BTCUSDT. api.bybit.com
[8] US Bureau of Economic Analysis, Personal Income and Outlays, August 2026, released September 30, 2026. bea.gov
[9] US Bureau of Economic Analysis, GDP (Third Estimate), 2nd Quarter 2026, released September 30, 2026. bea.gov
[10] US Bureau of Labor Statistics, The Employment Situation, September 2026, released October 2, 2026. bls.gov
[11] US Bureau of Labor Statistics, Job Openings and Labor Turnover, August 2026, released September 29, 2026. bls.gov
[12] Board of Governors of the Federal Reserve System, proposed rule, Implementing the Federal Reserve Board's Responsibilities Under the GENIUS Act, Federal Register document 2026-19860, September 29, 2026. govinfo.gov
[13] Board of Governors of the Federal Reserve System, proposed rule on application procedures for a subsidiary to issue payment stablecoins, Federal Register document 2026-19899, September 29, 2026. govinfo.gov
[14] US Treasury, interim final rule, Forms and Procedures for Review of State Certifications by the Stablecoin Certification Review Committee, Federal Register document 2026-19966, September 30, 2026. govinfo.gov
[15] Strategy Inc, Form 8-K filed October 1, 2026, accession 0001193125-26-409863, Item 8.01. sec.gov
[16] Strategy Inc, Form 8-K filed August 31, 2026, accession 0001193125-26-375463, Item 8.01, period August 24–30, 2026. sec.gov
[17] Strategy Inc, Form 8-K filed September 21, 2026, accession 0001193125-26-396093, Item 8.01, period September 14–20, 2026. sec.gov
[18] Board of Governors of the Federal Reserve System, FOMC meeting calendars, 2026. federalreserve.gov
[19] US Bureau of Labor Statistics, schedule of selected releases, October 2026. bls.gov
[20] TreasuryDirect, buyback announcements and results by operation date; not retrievable over a verified connection from this machine, see section 7. treasurydirect.gov
[21] US Bureau of Economic Analysis, release schedule. bea.gov